Bond-Market Pressure Tests Scott Bessent’s Economic Strategy
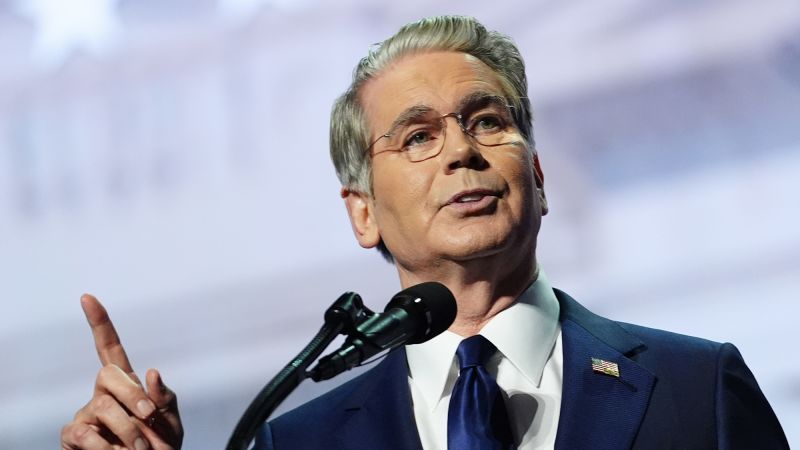
Goldlaner.com – Scott Bessent entered the Trump administration with an unusually strong reputation in global finance, a long record in markets and a willingness to confront critics directly. As Treasury secretary and President Donald Trump’s principal economic adviser, he has sought to project confidence that Washington can influence the cost of borrowing. But the recent path of Treasury yields has raised questions about whether that confidence can overcome the forces driving the world’s most consequential bond market.
Bessent had set an ambitious objective early last year: push the benchmark 10-year Treasury yield below 4%. Instead, yields have moved sharply in the other direction. On Tuesday, the 10-year rate briefly surpassed 5.04%, its highest level since 2007. That increase matters far beyond trading desks because Treasury yields help shape borrowing costs throughout the economy.
Higher yields can translate into more expensive mortgages, pricier loans for small businesses and rising interest costs for the federal government. Mortgage rates tend to move closely with the 10-year Treasury yield, and they have reached their highest point since June 2025.
A High-Profile Effort to Calm Yields
Last month, with market rates climbing, Bessent took a step that surprised many investors: Treasury buybacks were expanded to roughly three times their prior scale. The move was intended to help manage pressure in the bond market, but yields have remained higher than they were before the intervention.
Hardika Singh, an economic strategist at Fundstrat, argued that the effort produced the wrong market signal.
“It massively flopped. If anything, this may have made the problem worse. Bessent showed his hand. To investors, it was like, ‘Oh my gosh, he’s worried.’ We should be too.”
The episode has intensified a long-running debate over how much officials can do through market operations when investors are focused on the nation’s larger fiscal outlook. Treasury tools can affect market conditions, but they cannot by themselves erase concerns about inflation, debt issuance or the government’s future borrowing needs.
Deficits Remain at the Center of the Debate
Critics contend that the core issue is not a technical malfunction in the bond market but the persistence of exceptionally large budget deficits. Trump and Bessent had pledged to reduce the federal deficit to 3% of gross domestic product. Instead, deficits are running at approximately twice that rate, despite low unemployment and White House claims that the economy remains strong.
Douglas Holtz-Eakin, president of the center-right American Action Forum and a former top economist under President George W. Bush, said efforts to steer yields lower cannot succeed without addressing those underlying conditions.
“I don’t think you can fool mother nature. You’ve got to fix the fundamentals.”
Holtz-Eakin said Bessent’s yield-management initiative was bound to fall short because it did not resolve the prospect of trillion-dollar deficits extending into the future.
“They’ve made it worse. There’s no way around that.”
The debt challenge predates Bessent’s arrival at Treasury, and responsibility for it extends across both political parties. Still, the administration’s stated fiscal goals have made the gap between promise and outcome especially visible to investors who must decide how much compensation they require to hold government debt.
Why Bond Investors Matter to Households
The Treasury market is often treated as an abstract concern, yet its movement can be felt quickly by households and employers. When yields rise, lenders generally face higher funding costs and may charge consumers more for mortgages and other credit. A family looking to buy a home can see its monthly payment increase even if the purchase price stays unchanged. A local business seeking capital for expansion may find that borrowing becomes harder to justify.
Washington also pays more to finance its obligations when interest rates rise. Those larger financing costs can make future budget choices more difficult, particularly when deficits are already elevated.
David Wessel, a senior fellow in economic studies at the Brookings Institution, said intervention of this kind would make more sense if markets were suffering a serious breakdown and if it were accompanied by credible budget measures.
“But this isn’t a market-functioning-style emergency. It’s a politically inconvenient increase in yields.”
A Difficult Political and Economic Backdrop
Bessent’s supporters can point to the difficult conditions surrounding his tenure. Trump’s global trade war last year unsettled bond investors and complicated progress against inflation. Bessent has been credited with persuading Trump to pause those broad tariffs last spring, a decision that helped trigger a major rally in bonds and particularly in stocks.
More recently, the military conflict with Iran has added to cost-of-living pressures and contributed to uncertainty in financial markets. Tim Mahedy, chief executive of Access/Macro and a former official at the Federal Reserve Bank of San Francisco and the International Monetary Fund, said those wider policies have complicated Bessent’s task.
“He’s been taken for a ride by Trump’s chaos policy.”
Mahedy also argued that the administration’s actions have pushed yields in the opposite direction from Bessent’s intended goal.
“The data is clear. He’s added accelerant to the fire. He’s had the exact opposite impact that he wanted.”
Confidence Meets the Limits of the Market
Bessent’s public style has reflected his market background. He once helped George Soros profit from a major bet against the British pound in 1992, a trade that contributed to Britain abandoning its currency-support effort and generated more than $1 billion for Soros. In office, Bessent has told traders, “I am the house now,” and brushed aside criticism from “some of the Bloomberg Terminal bros.”
That posture may fit the competitive culture of finance, but the Treasury market ultimately responds to a broad set of forces: inflation expectations, federal borrowing, global demand for safe assets, economic growth and confidence in fiscal policy. The test for Bessent is not simply whether he can challenge investors, but whether the administration can persuade them that America’s economic fundamentals support lower long-term borrowing costs.
Related Reading
Frequently Asked Questions
What is The time Scott Bessent tried to outsmart?
The time Scott Bessent tried to outsmart is the main topic of this guide. The article explains the context, practical details, and next steps readers should understand.
Why does The time Scott Bessent tried to outsmart matter?
The time Scott Bessent tried to outsmart matters because readers are looking for a useful answer, not just a short summary. Good content should match search intent and help them decide what to do next.