A Milwaukee Couple Takes on Debt While Planning for a Different Future
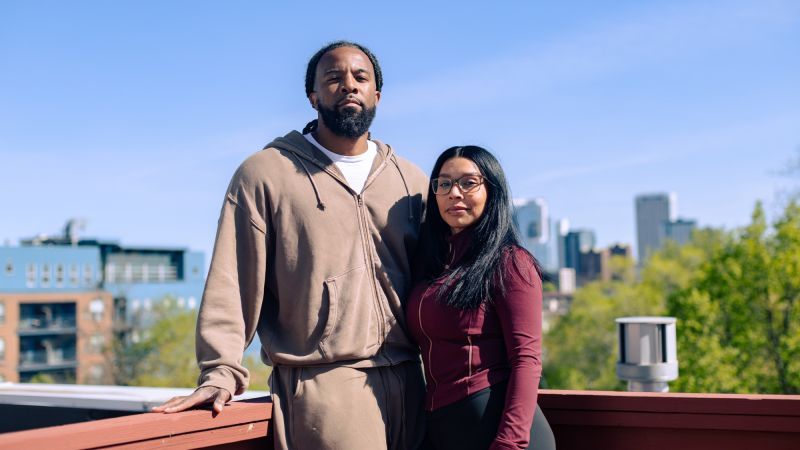
Goldlaner.com – Mariza and Geffrey Gordon want to move beyond the constant pressure of living paycheck to paycheck, but their path forward is complicated by nearly $40,000 in credit card debt and a sudden change in their household income.
The Milwaukee couple began a one-on-one financial coaching process as a dual-income household. Soon afterward, Mariza learned that she would be laid off and would receive only two months of severance pay. The news added urgency to an already difficult financial picture, one shaped by several debts and high monthly credit card obligations.
Much of the couple’s credit card balance came from paying for their wedding last year, Mariza said. Their minimum required payments alone total roughly $1,400 each month, leaving less room in the budget for savings, unexpected expenses and longer-term plans.
Focusing on the Most Pressing Financial Burden
Financial educator and budgeting specialist Tiffany Aliche met with the Gordons for an initial consultation. She came away impressed by how they approached the situation together.
“They were so supportive of each other,” Tiffany said.
She also viewed their willingness to ask for support as an important advantage. Many people remain trapped in difficult money patterns because they avoid reviewing the numbers or seeking guidance.
“Seeking help. A lot of people just stay stuck,” Tiffany said.
Because the coaching period was limited, Aliche determined that the couple could not solve every financial concern at once. Instead, she chose to concentrate on the issue creating the greatest strain: their revolving debt.
“The biggest thing weighing them down is their (credit card) debt,” Tiffany said.
Credit card debt can be particularly difficult to manage when balances carry high interest rates and minimum payments consume a major share of take-home pay. Even when borrowers make every required payment, balances may decline slowly if much of each payment goes toward interest. For a household navigating a job loss, reducing that monthly pressure can be as important as reducing the total amount owed.
Looking Beyond Debt Freedom
Before reviewing repayment options in detail, Aliche asked Mariza and Geffrey to picture what they wanted their lives to look like 10 years from now. She calls the exercise “dreamscaping.”
The goal was to help them connect their immediate financial decisions with a broader sense of purpose. Eliminating debt matters, she explained, but it is only part of building lasting financial stability.
“I wanted to give them something to work (toward),” Tiffany said.
Aliche cautioned that becoming debt-free does not automatically mean someone has built wealth, saved for retirement or created financial flexibility. Her recommendation was to reduce the feeling that debt is overwhelming their lives while keeping their attention on the bigger objective of growing wealth.
“Let’s get to a point where you don’t feel like your debt is drowning you. But the true goal is to grow wealth,” Tiffany said.
The conversation resonated with the Gordons. In the days after their first meeting, Mariza said the couple recognized how much their immediate stress had narrowed their focus.
“We were so caught up in the now and stressed about the present we hadn’t put thought into what we want for the future,” Mariza said.
Their long-term vision includes owning a home, eventually purchasing an investment property, taking occasional vacations, launching businesses of their own and building individual IRAs in addition to the retirement plans available through work.
Those aims illustrate why a financial plan often needs both short- and long-range components. A repayment strategy may ease today’s cash-flow burden, while savings, retirement contributions and future income plans can help create resilience once the debt is under better control.
Exploring Repayment Alternatives
Aliche encouraged the couple to investigate several options. One was contacting the National Foundation for Credit Counseling to learn whether a debt repayment plan could lower their monthly costs. She also suggested they explore a personal loan with an interest rate below their credit card rates or a balance transfer card.
The Gordons learned that a five-year repayment plan through the National Foundation for Credit Counseling could require monthly payments of $900. That would be $500 less than the $1,400 they currently pay in minimums.
The lower payment came with an important restriction: they would be unable to use revolving credit throughout the five-year plan. For now, the couple does not believe that arrangement offers enough flexibility, particularly given their need to preserve access to credit during a period of employment uncertainty.
“Given our situation, we don’t feel that option is the best fit for us right now, as we want to maintain some flexibility in case we need access to credit,” they said in an email.
They also contacted a credit union to ask about alternatives. Until their credit scores improve, they do not qualify for a personal loan with a favorable interest rate or for a balance transfer card. Such cards can offer as much as 21 months of interest-free repayment on transferred balances, depending on approval and terms.
Their immediate objective is now tied to improving their credit profile enough to qualify for one of those cards.
“We want to get our score high enough to get a balance transfer card,” Mariza said.
Their situation shows the difficult tradeoffs households can face when debt repayment, credit access and income uncertainty overlap. Lower monthly payments can offer breathing room, but they may also involve restrictions that do not work for every borrower. A lower-rate loan or promotional transfer offer can help in the right circumstances, yet approval often depends on the credit strength a borrower is trying to rebuild.
For Mariza and Geffrey, the next stage will be about turning their shared long-term vision into practical steps while managing the immediate demands of debt and a changing income situation.
Related Reading
Frequently Asked Questions
What is One couple wants to stop living?
One couple wants to stop living is the main topic of this guide. The article explains the context, practical details, and next steps readers should understand.
Why does One couple wants to stop living matter?
One couple wants to stop living matters because readers are looking for a useful answer, not just a short summary. Good content should match search intent and help them decide what to do next.